 Are you worried your credit score might stop you from starting your next investment project? Then a hard money loan could be the right option for you.
Hard money loans are asset-based, meaning lenders focus more on the quality of the deal and less on credit score.
They are also secured, which means they’re tied to an investment property. If you default on the loan, the lender can foreclose and take back the property. Suggesting that hard money loans are best suited for investors who are fully committed to the success of their project. This security makes commercial loans less risky for hard money lenders. And as a result, they may be willing to bypass credit issues when approving you.
Will your credit score help or hurt you when getting approved for a hard money loan? Learn how hard money lenders evaluate your credit score in our most commonly asked questions below.
 Rising in popularity, virtual staging is a cost-savings staging option amongst real estate investors in DC, Maryland, and Virginia. For half the price of traditional staging, investors are teaming up with virtual stagers to bring life and personality to their properties. Where investors pay traditional stagers monthly until their property is sold, those who opt for a virtual stage only pay 1 upfront fee. But are potential buyers disappointed when they get to a property and see no furniture? Senior Sales Associate, Gunnar Sevart sits down with virtual staging professional, Bryant Payden to discuss the major advantages and obstacles the virtual staging industry is facing. If you’re looking to virtually stage your next flip check out Bryant’s website: https://novarealestatephoto.com/
Are you looking for a trusted and secure hard money lender to secure your next deal? Let’s get started!
 Hard money lenders can be an excellent source of capital for real estate investors, but it’s important to know how to tell if they’re legit. Claims like “we’ll lend on anything” or “we don’t require a down payment ” are major red flags that should make the investor think twice before using that lender. Below are a few guidelines to follow when looking for your next legitimate hard money lender.
Looking for a trusted and secure hard money lender to fund your next deal?
 Securing a loan to flip a property is probably easier than you think. From hard money lenders to private funding, you have multiple options available to fund your flip. Using a lender to fund your flip allows you to get started making money on properties without saving up the full amount needed for purchase. Each type of lender has their own set of strengths and weaknesses based on how fast they can close, and what their interest rates are. So, let’s dive into the pros and cons of each lending option so that you can find the right source of funds for your next flip.
| Pros | Cons |
|---|---|
| Fast closings | Higher interest rates than most banks |
| Flexible loan structuring | Require credit check and borrower history to structure loans |
| Experience and operational knowledge in the house flipping industry | |
| Proven ability to vet deals and correctly manage construction funds |
| Pros | Cons | |
|---|---|---|
| Low interest rates | Variable amount of industry knowledge | |
| Fewer regulations and less paperwork | Variable experience managing construction funds | |
| Experience and operational knowledge in the house flipping industry | ||
| Variable amounts of capital available | ||
| Potential to damage relationship (if funds are coming from friends or family) |
| Pros | Cons | |
|---|---|---|
| Some of the lowest interest rates available | Slow to close due to red tape and heavy regulations | |
| Require high credit scores for approval | ||
| Lack experience and operational knowledge in the house flipping industry | ||
| Unlikely to loan on a highly distressed properties |
Investors use hard money loans to finance short-term real estate investment projects and rental properties. They obtain these loans to rehab distressed properties better known as “fix and flips” or to secure a “buy and hold” rental property. A hard money lender will generate your loan based on the property you’re using as collateral, as well as borrower factors like your credit score and level of experience in real estate investing. Before you seek out financing for your next project, make sure you understand all of the advantages and risks of using hard money.
Here’s a short-list of all of the benefits and drawbacks you may experience when using a hard money loan. Keep reading for an expanded explanation for each hard money lending pro and con.
| Pros | Cons |
|---|---|
| Fast Closings & Quick Approvals | Medium-High Interest Rates |
| Low Credit Scores Accepted | Down Payment Required |
| Funding Fix and Flip Properties | Points Paid Up Front |
| Partnership | Extension Fees |
| Free Underwriting | Foreclosure/Default |
| No Pre-Payment Penalty | |
| Off-Market Properties |
Hard money loans are often perceived as financing for investors with bad credit history. While this isn’t always true, a hard money loan can benefit you whether your credit is excellent or poor. Continue reading to learn the benefits of using a hard money loan.
There are fewer requirements for getting a hard money loan approved than conventional bank loans. As a result, you can get a hard money loan funded in as little as 24 – 48 hours. Where banks will spend 30+ days structuring a loan based heavily on credit score, hard money lenders spend less time configuring a loan based on the profitability of a property. Furthermore, if you have a working relationship with a lender you can receive other benefits such as faster closings and paying fewer origination points.
It’s no secret that banks will decline someone for having a low credit score. Hard money lenders, on the other hand, make decisions based on the profitability of the subject property and less on credit. Investors with a credit score of 620 or higher are typically approved for a hard money loan. If an investor’s credit score is lower than that, they’ll likely need to explain the situation to the lender, but it still might not be a deal-breaker.
A typical fix and flip property is one that is vacant and outdated – qualities that enable investors to buy at a low price. Although riskier, hard money lenders recognize the fact that distressed, neglected properties typically offer high-profit margins. As a result, lenders will often fund them after breaking down the numbers.
Banks, on the other hand, are risk-averse meaning they can’t lend on a property that goes beyond their lending criteria. Properties considered ‘uninhabitable’ are not eligible. Like comparing apples to oranges, hard money loans cater specifically to investors with these types of properties whereas banks do not.
Hard money lenders are a great resource for contacts, advice, and guidance on deals. They can point you in the right direction for reputable contractors, title companies, stagers, agents, and how to meet them. Also, they’re a great resource for finding comparables and most can evaluate your deal for free. Gone are the days you use a lender just to get access to capital, investors are now looking for reputable lenders to form an ongoing partnership with.
To acquire a hard money loan, an investor must get pre-qualified through a lender’s underwriting process. During this process, the lender determines the overall risk of the loan and the profitability of the deal. Credit score, experience, and collateral are all components a lender takes into consideration. Most lenders in the area offer a free underwriting, but not all.
Borrowers who complete their project early have the option to pay back their loan earlier than the 12-month loan term. Most lenders do not charge a prepayment penalty. On the other hand, conventional loans charge lower monthly interest but tend to make up their losses in a hefty pre-payment penalty. Investors that finish their project early can save money on interest payments and get into their next project quicker.
Off-market properties are properties that are sold by wholesalers. A wholesaler is an individual who finds an off-market property, secures it with a contract, then resells to another investor in a matter of days. These properties are not publicly advertised online or on your local multiple listing service. If you’re in the market for a property to rehab, see if your lender can connect you with any local wholesalers.
Now that you know the most common hard money lending pros, let’s talk about the drawbacks. Hard money loans come with fees and rules on how to use the funds. When making the decision to use hard money lending as your source of capital, make sure you’re considering all of the common barriers we’ve listed below.
Interest rates on a hard money loan range between 7 – 12%. Even if a deal is solid, a hard money lender is still taking on more risk by lending on a distressed property. Banks offer lower rates because they are typically lending on low-risk properties like owner-occupied primary residences with little to no construction needed.
For a fix and flip, investors are typically expected to bring at least 20% of the purchase price at closing. If you’re a novice investor, it can be hard to come up with this money, especially if you’re looking to flip in areas like Northern Virginia and DC where properties are more expensive.
1) Reduce their risk of default/foreclosure
2) To incentivize investors to complete the project
The reality is that investors who have “skin in the game” are less likely to walk away from the project mid-rehab.
These are the fees a borrower pays in order to use a lender’s money and the time it takes for the lender to put together the deal. At closing, the borrower pays 2-5 percentage points of the total loan amount.
For example, 2 points (2% of the loan amount) on a $300,000 loan would be $6,000. Borrowers who benefit from fewer points typically have more experience, a great deal, and an executable plan from beginning to end.
The length of a loan is typically 12 months. Borrowers are contractually required to complete their flip, sell the property, and pay back the lender within that amount of time. Issues can push a project’s timeline back, causing a borrower to request a loan extension.
Hard money lenders are generally flexible when asked to grant an extension. However, borrowers should be ready for the consequences that come along with an extension. Examples of these consequences could include increased monthly interest payments and extension fees.
The risk of foreclosure is very similar to a conventional mortgage with a bank. Unpaid monthly interest payments, failure to maintain or repair the property, and an unpaid loan are all reasons a borrower could be facing foreclosure. Because taking a property back mid-rehab is very costly for lenders, most are willing to help borrowers figure out a game plan for finishing the project as originally planned.
If your project isn’t folding out the way you want it to and you’re fearing default/foreclosure the best thing to do is to communicate your issues with the lender. And if you stop communication you’re more likely to lose the property.
Avoid a lot of the risks mentioned above by understanding the lender’s terms and fees. Also, having a strong exit strategy in place and committing to on-time payments will help you build a lasting relationship with a lender. Finally, once you’ve proved to your lender that you’re a safe investment by successfully completing a project, it is possible to receive lowered rates and lowered origination points.
As the Largest Hard Money Lender in the Mid-Atlantic, Washington Capital Partners offers investors fast closings, low rates, and superior service to help you reach your investing goals. Our underwriting process is completely free and is done in as little as 48 hours. There is no obligation to continue with the loan, so this is a great resource for investors that need an expert’s opinion when evaluating a deal.
You made the decision not to stage and now your flip is sitting on the market longer than you anticipated. You think to yourself, “All the work I put into creating an open floor plan unique to this area, how have I not closed a sale yet?” Real estate investors and buyers see properties through different lenses, and just because you can picture where the coffee table, couch, and chairs will go, doesn’t mean the buyer will.
At our last CAZA Investor Meetup, we noticed that there isn’t really a general consensus when it comes to staging. Some investors say always make room for staging in the budget and others opt for light staging or virtual staging to save a little money. The whole point of house staging is to help a buyer visualize themselves living in the house. Each room in your flip should outline that room’s purpose with the goal of having a buyer’s imagination run wild picturing themselves living in the space. Even if the price of the house is a little on the high side, if you won the buyer’s heart over by staging you successfully increased your chances of getting that sale. I know what you’re thinking – hiring a professional stager is pricey! But thankfully staging isn’t always necessary. When people ask us, our rule of thumb is the more expensive the property, the more important staging is. That being said, run-of-the-mill remodels do not always need staging. If your flipped property is very similar to its comparables then staging might not be worth it. But if you’re shooting for the highest price in the neighborhood, then yes you’re probably going to have to dress it up more. “A potential buyer only needs 6 minutes or less to form a lasting opinion about a house on the market…If you fail to impress a buyer within the first few minutes, what makes you think it will be easier to convince the buyer to purchase the property ten, twenty, or thirty minutes later?” – Parker Alex, AuthorHere are some questions that can help you determine if staging is a must for your property:
1. Will potential buyers fall in love with your home from the street? If not, stage it.
2. Does each room have a clearly defined purpose? Would your target market prefer a room be an office or a playroom?
3. Will professional staging give you a higher return?
4. How is the competition with comparable properties in the neighborhood? Will staging give you the upper-hand?
5. Do you have an open floor plan? Is it difficult for buyers to imagine the empty areas furnished?
6. Does the house look kind of bland and boring without any furniture or decor? Stage it.
Once you decide you are going to stage; then you need to figure out if you’re going to fully stage, light stage, partially stage, or virtual stage.
Fully staging is using furniture and decorative items to fully suggest a function for each room.
Light Staging is vaguely suggesting a use for key rooms but keeping it very light with artwork and other decorative items.
Partially Staging is a combination of light staging and fully staging only in rooms where the buyer may need help visualizing it furnished. Staging the living room always has a positive effect on the buyer because they can easily envision themselves relaxing and enjoying time in that space with their families. But other rooms such as the kitchen that already has impressive features like upgraded counters and high-end fixtures and appliances can be left to speak for itself.
Extra bedrooms don’t always require staging either. Once the buyer has already had a positive experience throughout the tour and reaches the extra bedrooms, they’ll already have an opinion on how their lives will fit into the house. Ditching generic blinds for some flowy curtains could be all a room needs.
How about an option that costs less and still gets buyer’s in the door? Approved for the MLS just last year, virtual staging is a creative tool for investors to quickly bring in a qualified buyer. Virtual staging will bring life to your property, just make sure to follow the MLS’s rules for posting and to find a reputable company.
Deciding to stage your property involves a lot of research, a look at your return on investment, and thinking like a buyer. With these tips, you can get potential buyers in the door and sell your house faster so you can move on to your next project.
 Plenty of realtors have an invaluable set of skills that make them a staple within the industry. These skills allow realtors to hunt down the best deals for their clients, weigh the pros and cons of each property, negotiate the best price, coordinate the contract paperwork, find the perfect buyer, the list goes on and on. But what if a realtor becomes their own client? That realtor can then invest (spoiler alert) all of those skills into their own wealth. This is why realtors make some of the best real estate investors around – they already bring so much to the table. So, let’s take a look at why realtors should consider becoming investors.
They can assess value
One of the first things that agents learn is to analyze the value of a property. Comparing the property as-is to what it could potentially be, and determining how much time and money it would take to get there is a cornerstone of both the realtor and investor worlds. How many of us have heard a realtor say the following to a client?
“It could use some work, but there is a lot of potential and the price is right.”
Sounds familiar, right? Well, that ability to analyze an as-is property is a starting point for both the agent and the investor. And when an agent says, “with some updates, you’ll immediately have equity in the home,” they’re estimating the After-Repair Value (ARV), just like an investor.
They’re constantly driving neighborhoods
A trained realtor knows just how important a neighborhood is to the sale of a home. So, most agents spend a fair amount of time driving neighborhoods, checking out other properties for sale, and becoming familiar with the immediate area. Most agents will make note of the number of distressed or foreclosed properties near their appointment, since this could hurt the sale of that home. Investors, on the other hand, are driving neighborhoods because they want to see these dilapidated properties and foreclosures. This is where they strike gold – the worst house on the block. Whether realtors know it or not, they are already “driving for dollars,” the common term for hitting the streets and looking for investment opportunities. The only difference is that when a realtor sees an eyesore, an investor sees potential profits.
They’ve got access to the MLS
One of the most powerful technologies available to an agent is their Multiple Listing Service (MLS). In each part of the country it may go by a different name (for the DC Metro area it’s “MRIS, a Bright MLS”), but these databases are indispensable to the agents using them. As good as the free listing sites may claim to be, the MLS database simply has more info and a higher level of accuracy. Realtors can easily use this wealth of knowledge at their disposal to target investment properties by searching the MLS for Real Estate Owned (REO’s) and short-sales. Another way to use the MLS to find investment property deals is to find the average property value in an area, and simply search all properties with a lower value. The MLS is a powerful tool, and with new tools and platforms being created, its only getting better.
They have an existing network
Building a network of industry players (buyers, sellers, investors, contractors, etc.) is important in order for a realtor to deliver more value and win more business. Having this network in place when an agent decides to begin investing will give them a huge advantage over most newbie investors that are starting from square one. Most investors will pay an agent (eating into their profit margins) just for access to their network of buyers. As an agent, you keep more profit and already have a network at your fingertips.
They can keep more profits AND make commission
Let’s say you’re a realtor that invested in a property, rehabbed it, and you’re ready to sell. Serving as the listing agent, you will already be collecting one commission, but what if you have a client who wants to purchase your newly renovated property? Double commission – every agent’s ideal scenario. Profits from a flip AND double commission? That’s a perfect storm of income that ‘realtors-turned-investors’ can achieve.
They’re constantly getting market feedback
Every transaction, open house, property tour, and client interaction that a realtor experiences creates a dynamic picture of the current housing market. The very nature of a realtor’s work keeps them updated with what areas are booming, what properties are in high demand, and what features are selling right now. The day-to-day of a realtor’s job inherently makes them a more educated investor. This can help them make better decisions on what neighborhoods to invest in, what appliances to purchase, and what color scheme will provide the most curb appeal. Agents tend to know the buyers of rehabbed properties better than anyone because, frankly, they get facetime with buyers on a daily basis.
They know how to negotiate a contract
This one may be a bit more subjective, but any good realtor has experience negotiating and purchase and sale of a property for maximum value. A new investor who lacks this experience can destroy their own profit margins simply by failing to negotiate a lower purchase price and being bullied by aggressive buyers on the back end. Most realtors know this game and have spent their whole career sharpening their negotiating skills.
They can diversify their income
Real estate has both seasonal and longer-term cycles. Realtors know this better than most since their income often reflects the market fluctuations. By becoming an investor, realtors can diversify their income, receiving cash injections from flips, and steady, long-term income from rentals. The long-term rental income may be especially appealing to realtors since most agents don’t have a traditional retirement plan provided by their agencies. So without a pension plan or 401k matching, realtors can look to investing as a means of retirement planning and estate building.
Most realtors already have a great foundation for an investing career. With so many tools at their disposal and a chance for investment profits PLUS commission, agents just have to ask themselves, “what’s holding me back?”
Capital gains taxes – three words that can make or break an investor. These after-the-sale taxes on the profits from selling investment properties can be as high as 30% when you add up both state and federal taxes. Ouch, there go your profit margins. So how can an investor avoid them? One strategy is to utilize the 1031 Exchange to defer those taxes while keeping your money invested in real estate.
The 1031 Exchange is a powerful tool for investors, making it a favorite among many savvy and successful real estate pros. Here are the basics of the 1031 Exchange:
The first half of the exchange is the property you currently hold. In order to qualify, this property must be held for business or investment use – meaning no personal residences. What about fix and flips? The answer is typically “no” because the intent of most flips is to acquire, rehab, and sell within a short period of time. In the eyes of the IRS, this does not fit their criteria for eligible properties. But fear not rehabbers! You can still utilize a 1031 Exchange if you rehab a property and rent it out before selling. The IRS sees this as a long-term investment property, and therefore eligible for capital gains tax deferment.
At WCP, we have solutions for investors looking to acquire, rehab, and rent out an investment property so that it can qualify for a 1031 exchange. To secure and rehab the property, you can utilize a Fix and Flip Loan, and when the construction is complete you can refinance it into a Rental Loan with a 30-year term. This allows you to flip a house using hard money, and qualify the property for a 1031 Exchange by holding it as a cash-flowing property, all with one lender, minimal documents, and minimal effort. Boom.
The second half of the exchange is the property that you intend to acquire. This property must be of “like-kind” to your current property, meaning the property must also be an investment, not a personal residence. Qualified property types include, but are not limited to, office buildings, shopping centers, mixed-use properties, multifamily properties, single family homes, and even undeveloped land. Another option that you can utilize would be a “Tenants in Common” property. So if you currently hold a multifamily rental building, you can potentially use the 1031 Exchange to sell that property without paying capital gains taxes, and reinvest in undeveloped land (since it is still considered “like-kind” property).
According to 1031 Exchange guidelines, you will likely need a Qualified Intermediary (QI) to serve as a third-party to accommodate the sale, and hold subsequent payout from your currently held property. The QI also purchases the replacement property on your behalf before deeding it over to you. The entire exchange is facilitated by the QI, and they are the ones hanging on to your money before the replacement property is purchased, so be sure to choose a reputable QI. The demand for legitimate QI’s has led to the creation of businesses, usually tied to title companies, that provide QI services. This is a great place to start, but always ask for references and do your due diligence before picking one for your exchange. While it may not be a flat-out requirement, I highly recommend that you utilize a QI to ensure that your transaction is done correctly and your exchange doesn’t fall through because of title or escrow issues that can be avoided.
To properly execute a 1031 Exchange, you need to plan ahead. Once the sale of your currently held property takes place, the clock starts ticking on your first time restriction. At that point, you have 45 calendar days to identify your replacement property. The rules allow you to identify 3 (there are some exceptions to that limit) potential replacement properties within the 45-day window, but here’s the catch – one of those identified properties must be the one that you close on. In the world of real estate investing, 45 days feels like the blink of an eye for vetting and selecting properties, so how are you supposed to ensure that you meet this restriction? The answer is to plan ahead. Before that 45-day window even starts, you should be doing all of the necessary legwork to line up your replacement property. The goal here is to set up your timing so that you have your desired replacement property under contract the minute your currently held property closes, and that 45-day window begins. That way, even if the first contract falls through, you’re giving yourself the maximum amount of time to fall back on your next identified property.
Now if a buyer stepped forward for your currently held property as a surprise, planning ahead isn’t going to be very easy. In that scenario, you will probably have to be quick on your feet and highly organized if you want to identify your replacement property just 45 days after your currently held property closes. This isn’t impossible, but it can be hectic.
Your second time restriction also starts ticking as soon as you close on the sale of your currently held property. From that time, you have 180 days to close on the selected replacement property. That’s right, both time limits are activated on the same day, so be mindful that your 180-day limit is not influenced by your 45-day Identification Period. Also, know that no extensions or exceptions will be granted – you have 180 days and not a minute longer. The only event that can change this time limit would be the due date of your tax return. If your return is due before the end of your 180-day window, then that date becomes your new time limit. This is why I can’t stress enough how important planning out your 1031 Exchange is!
Yes. Deferring your capital gains taxes is absolutely worth the work. If you intend to keep your money invested in like-kind real estate, you should never have to pay capital gains taxes. With the right planning and guidance from expert counsel, you can defer these taxes indefinitely while holding positive cash-flowing properties throughout your investing career. In theory, you can keep deferring capital gains taxes through 1031 Exchanges until the day that you die. This means that you escape paying the taxes, and your heir receives the property free from the taxes that you owed. This makes a 1031 Exchange a powerful tool for building a cash-flow portfolio using pre-tax dollars and protecting your estate from the IRS. Now that’s a win-win scenario.
Please note – This blog was written to give you as much useful information as possible but is not intended to be treated as legal advice. It’s always best practice to seek out the guidance of experts!
 There’s a log cabin with an above-ground pool in the middle of Petworth according to Zillow. That sounds silly, doesn’t it? Check out the listing: https://www.zillow.com/homedetails/4406-Kansas-Ave-NW-Washington-DC-20011/477869_zpid/
And here’s what s really there:
I came across this the other day and asked myself if there’s a log-cabin falsely listed in the heart of DC’s hottest area for flipping what else is incorrect on these free house value sites?
Curious about what other people think about the legitimacy of sites like Zillow, Trulia, Redfin, etc., I asked the WCP team and took to BiggerPocket’s forum. I’ve found there’s an ongoing debate in the REI community about whether or not to use these free house value sites to find comps. Some investors refuse to use these sites at all, sticking to the MLS and others who don’t have access to the MLS use them to find “ballpark ranges” for their comps. What I’m going to share below is not to discourage the use of these sites, but to encourage the use of these as only “reference sites.” If you’re going to utilize these sites, I advise against using them as your main source for obtaining comps. Instead, use a listing’s information as a “reference.” As you now know with my log cabin example, property listings can be completely inaccurate. After I saw the log cabin pictures on Zillow I searched the same address on Redfin and found their listing had the correct pictures of the rowhouse: https://www.redfin.com/DC/Washington/4406-Kansas-Ave-NW-20011/home/10041618 Even with the correct pictures, you can see that the Redfin listing is missing the last sold price. It’s time-consuming but very important to cross-check a listing on several websites to determine if the information is consistent and accurate.So why the lack of consistency? I did some research and found 2 main reasons:
First, the algorithm that sites like Zillow, Trulia, etc. use for their estimates (ex: Zestimate) are unable to determine which neighborhoods within a 2-mile radius are the most similar. Regardless of if your subject property is in a cul-de-sac or situated on a busy road, the algorithm simply draws an invisible circle around the property and uses everything in it to determine value. This means that the comps generated by these sites are not nearly as similar as your subject property. Second, new investors need to understand that these websites are not pulling information from the MLS. They are third-party listing portals that agents use to advertise their listings. Once a house has sold, the listing agent should manually go back to the website and update it. Often, this doesn’t happen and the listings are dated and incomplete. This doesn’t mean that all properties on these sites have inaccurate information, but when it comes to generating accurate comps for your next deal, it’s simply not worth the gamble. The debate may go on about which free house value site is better but overall there is a consensus on the MLS being the best way to get accurate information on a property. What makes the information on the MLS so accurate is the system of checks and balances in place. Agents are listing properties, physically accessing them, and updating wrong information. To discourage inaccuracy, fines can be given for wrong information. If you’re not an agent and don’t have access to the MLS, the best way to get accurate comps is to cultivate a relationship with a realtor. Most realtors are willing to pull comps for you if you bring them your business. But don’t trust comps pulled by anyone. I’ve heard of realtors specifically picking comps with the highest value over others, benefitting them more than you. Make sure you are properly vetting any agent you want to join your team and telling them exactly what you’re looking for in potential comps. Another way to obtain comps is to ask us! Our Sales Executives understand the areas, have access to good quality comps and can provide you with them free of charge. We understand how crucial it is to get the most accurate information when determining the profitability of your next flip and we’re here to help!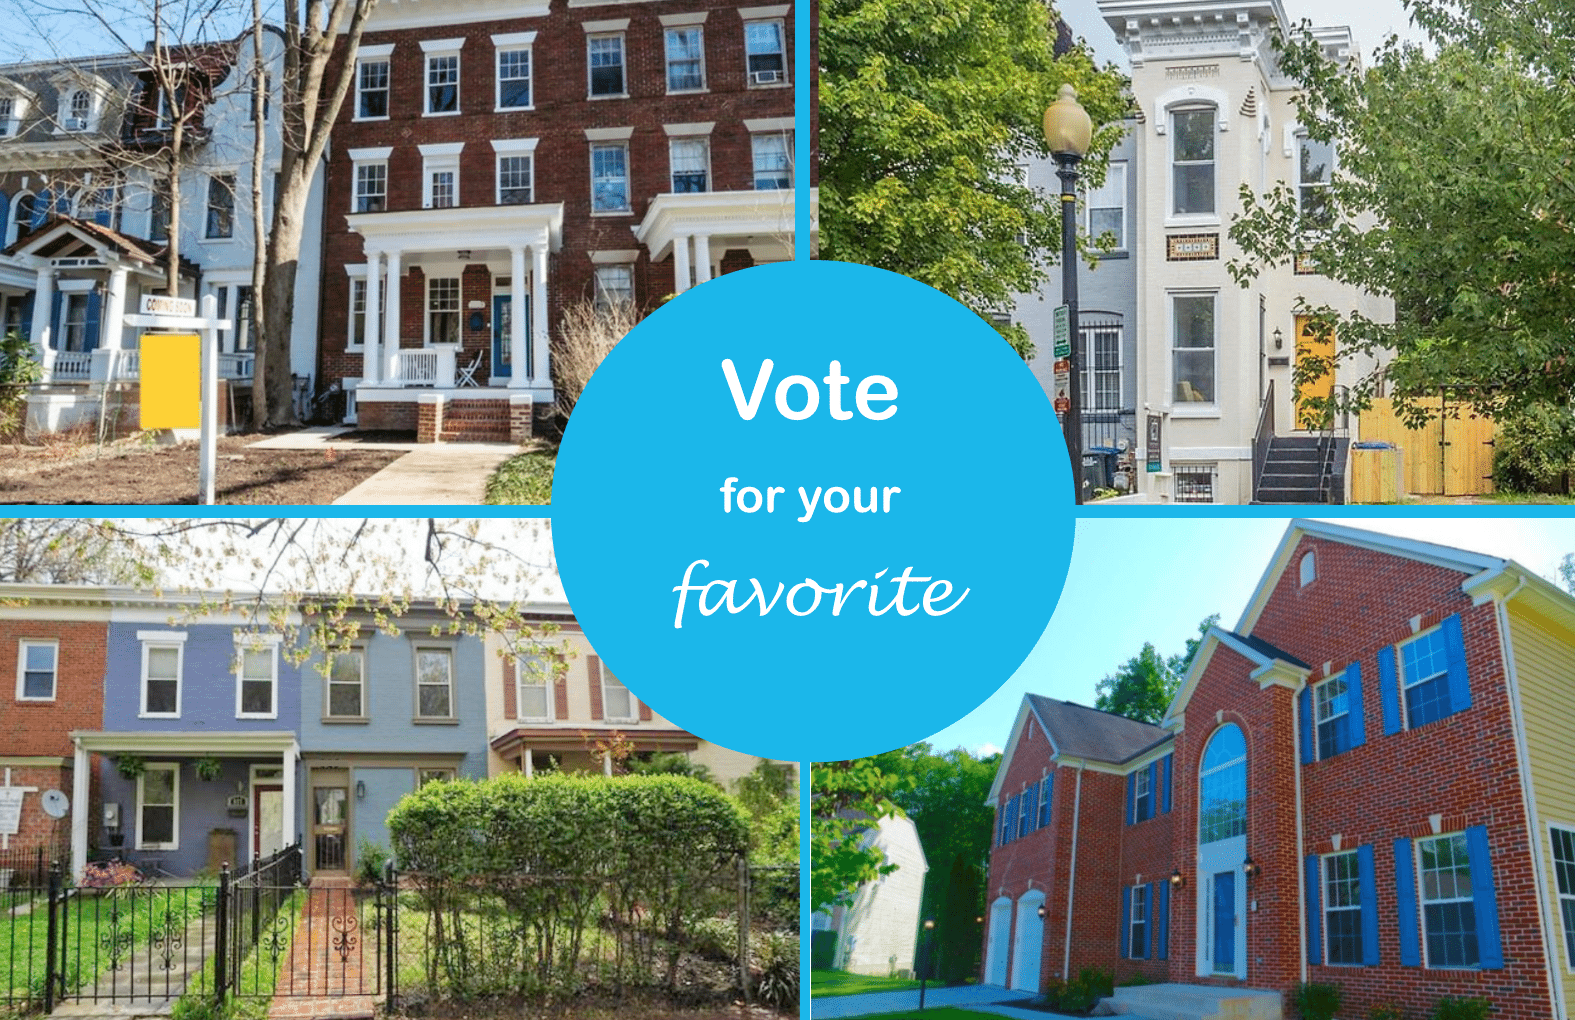
From a row house in the heart of DC to a neglected single-family home in PG country, we’ve funded 262 projects this year worthy of attention. Which one stands out the most?
Each week we shine a spotlight on a flip with contemporary features, efficient design, or neighborhood features. Never miss a #TransformationTuesday here. Take a look at the rehabs, and cast your vote for the Flip of the Year!